Hello. This is Stanton Jones and Sunder Sarangan with what’s important in the IT and business services industry this week.
If someone forwarded you this briefing, consider subscribing here.
What You Need to Know
Over the past three years, managed services contract value in EMEA has grown faster than in the Americas. However, that growth is concentrated in a few industry verticals.
Background
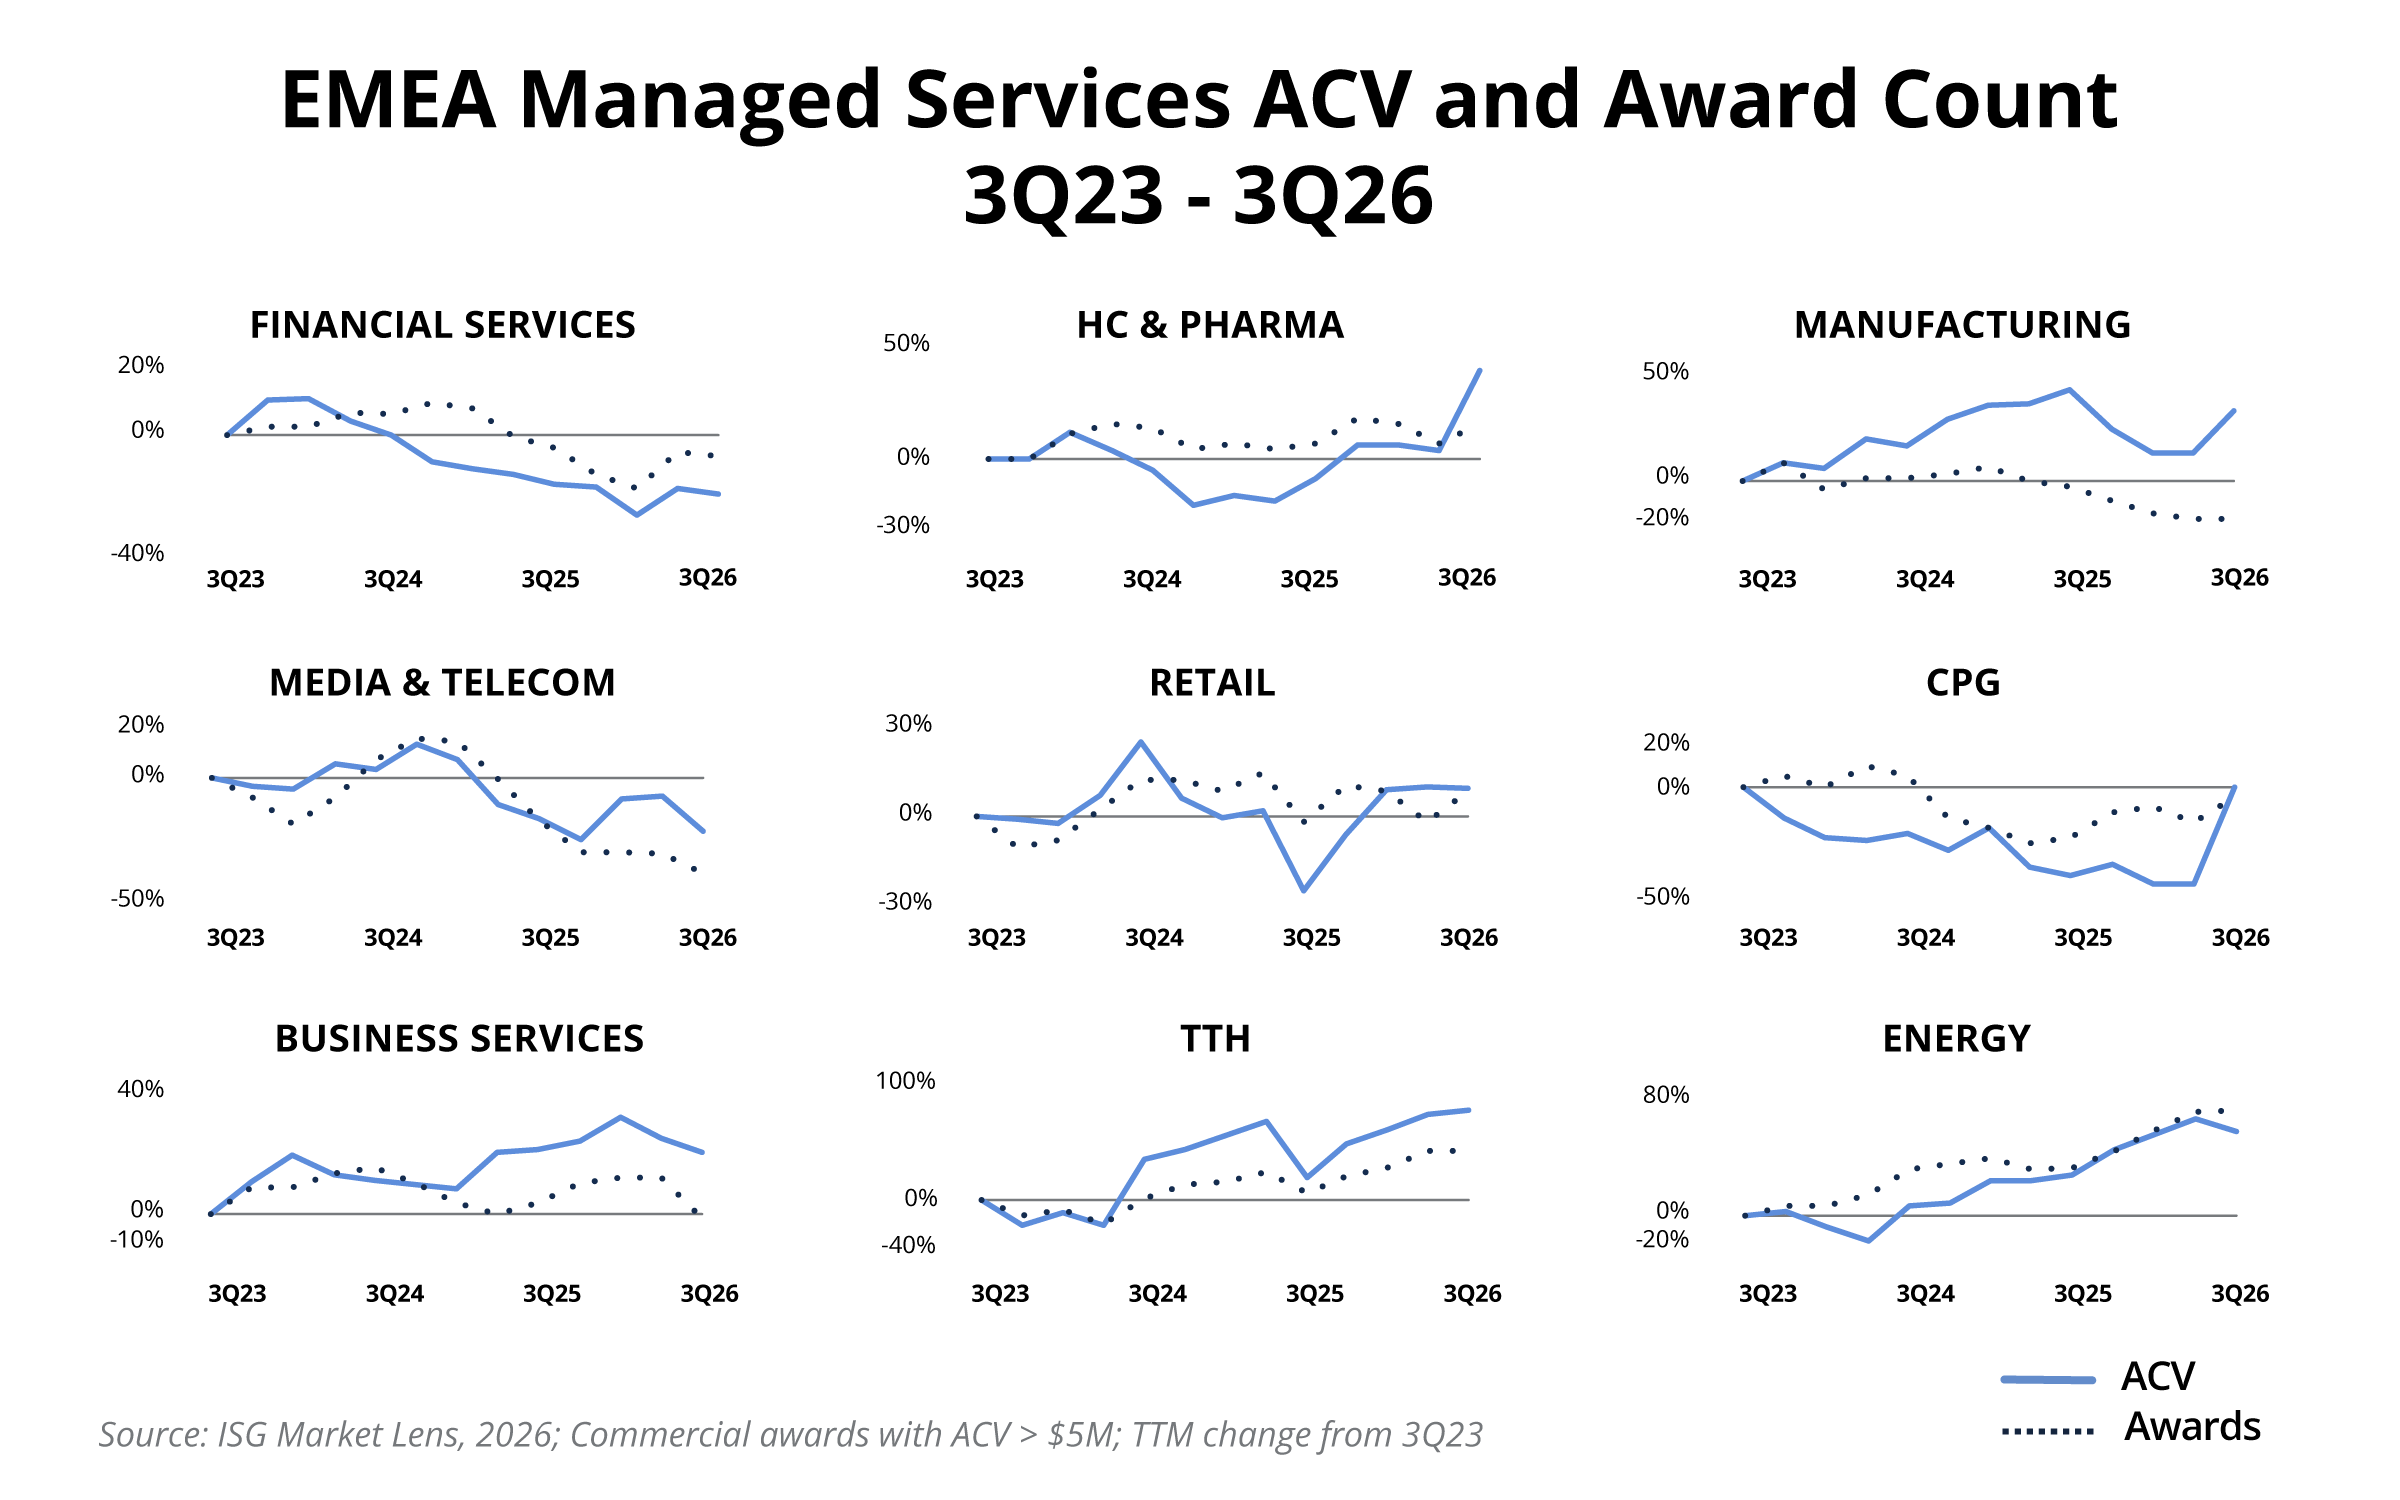
As we discussed last week, annual contract value (ACV) in the Americas is up 5% over the past three years. Meanwhile, EMEA has seen much stronger growth – ACV is up a very robust 17% over the same period. However, that growth is concentrated in industries like energy and travel, which is offsetting weakness in others, like financial services, media and telecom.
Sustained Growth
Energy and travel have seen both awards and ACV increase steadily since 2023. Travel ACV is up 80% over the last three years, even with a significant dip in 2025. That said, energy has been the more consistent of the two industries, with awards up nearly 70% and ACV up just over 50% since 2023. Growth in awards and in ACV here is an indicator of strong demand for IT services in both these sectors.
Manufacturing and business services have seen strong ACV growth; however, award counts are trending downward. Manufacturing ACV is up 31% since 2023, while business services ACV is up 19%. That said, award counts have declined in both sectors. Strong ACV growth combined with flat or shrinking award counts is an indicator that award sizes are increasing.
Down but Recovering
CPG, retail and healthcare saw significant declines in ACV in 2024 and 2025, but all three sectors in EMEA have been on an upswing as of late. The recovery in these sectors has been relatively recent, so we’ll need to see two or three more quarters of consistent growth in awards and ACV to determine if demand is fully recovering in these sectors.
Under Pressure
Financial services and media & telecom have seen both contract value and award counts decline over the past three years. ACV is down more than 20% for both sectors, while award counts are down 8% and 43% respectively. When both ACV and award counts decline, it’s often a signal that demand is softening. BFSI and media & telecom are the most mature industries in terms of their use of outsourcing, so this may be an early indication that firms in these sectors are focusing on “building before outsourcing.”
Given these results, one of the biggest concerns for the IT services sector leading into 2027 is financial services. It accounts for around 20% of the ACV in the market and is under pressure in both EMEA and in the U.S. And, when interest rates rise, more often than not, it has a negative impact on technology spending in the BFSI sector. And, by most accounts, it appears we’re headed into a higher interest rate environment in 2027.
About the authors
Stanton Jones