Hello. This is Stanton Jones with what’s important in the IT and business services industry this week.
If someone forwarded you this briefing, consider subscribing here.
What You Need to Know
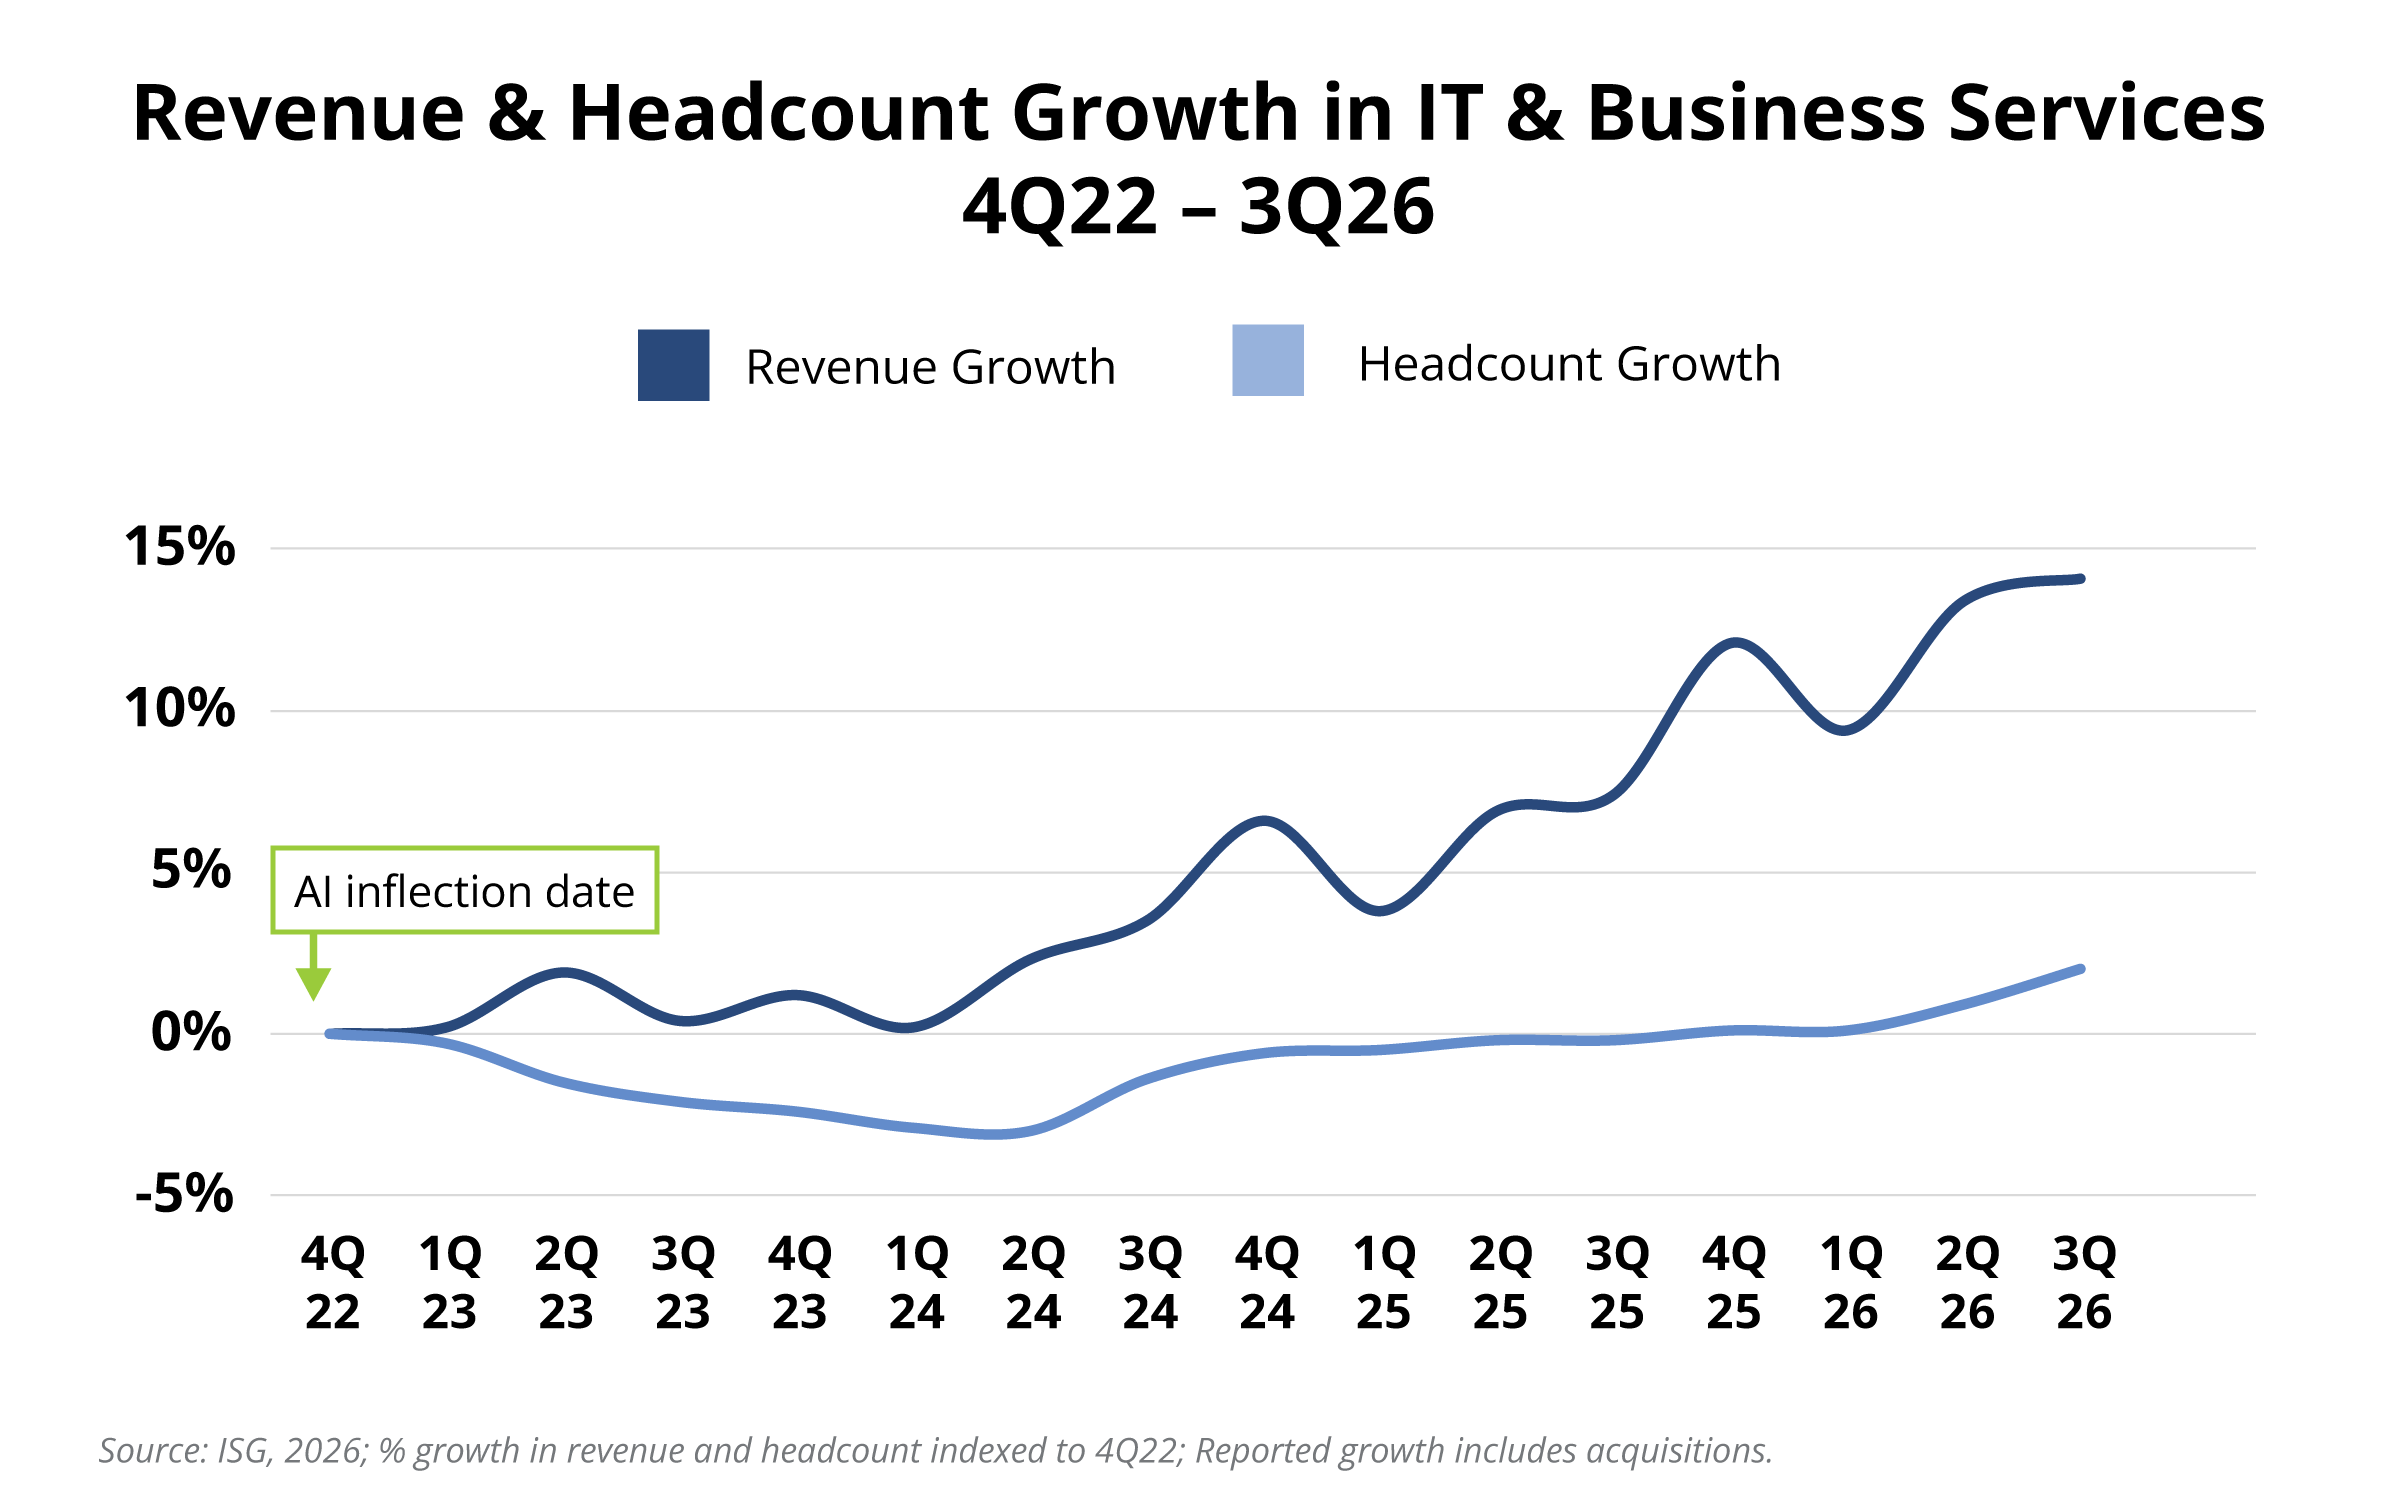
Revenue growth continues to outpace headcount growth across our service provider coverage universe. However, in Q3, revenue growth slowed while headcount growth accelerated.
Background
As we discussed back in June, the signals around revenue and headcount growth in the IT and business services sector were mixed: headcount was flat, while revenue was down. We posited that this was less likely due to AI and more likely due to the combination of muted demand, relatively low attrition and high utilization levels.
The situation looks different today. As you can see in this week’s Data Watch, headcount growth turned positive over the last two quarters (the first growth in headcount since the AI inflection point in 4Q22) while revenue growth is up slightly.
The Details
- Revenue growth in the sector is up 14.1% since 4Q22 and is up slightly from 2Q26.
- Headcount growth, meanwhile, is up 2% compared to our AI inflection date.
- Other metrics like attrition and utilization are stable.
What’s Next
Given that we’re nearly through Q3 earnings season, most providers have indicated that demand is broadly stable, with data and AI driving growth. However, providers also say they are seeing some clients delay decisions because of AI while discretionary spending remains tight.
That’s translating into low single-digit growth for many providers in the sector and is one of the reasons we held our managed services forecast at 2.1% for the full year.
So, if clients are remaining cautious, and some work is getting delayed to AI, why is headcount up, if only even slightly? It can be due to a lot of reasons: large deals are ramping up, utilization has been running hot for too long, demand for new AI modernization work, etc.
But it’s also clear that AI is changing the work providers need to perform for their clients. Will that work need fewer people? Yes, it’s likely. But it most certainly will require new skills. A lot of those skills will include working with and alongside AI, while continuing to support enterprise clients that are not yet ready to modernize.
This means that providers – just like their clients – are likely to be in an environment where they’ll be rebalancing their skill profiles via headcount changes, retraining, redeployment and attrition for some time to come.
About the author